

Another one.
That was my reaction when I saw that Ascend Elements filed Chapter 11 on April 9, 2026.
The company had raised over $1.1 billion, but its Kentucky facility stalled at 60% completion, contractors were owed over $145 million, and a $316 million DOE grant was pulled.
The new CEO, who joined in March 2025 and substantially refreshed the senior leadership team, described what he inherited as a “long history of fiscal and operational mismanagement.”
Three weeks before that, 24M Technologies shut its doors without a filing or a press conference.
The U.S. battery start-up, valued at over $1 billion, was built around an IP licensing model in which only Kyocera in Japan was producing batteries using its technology, with plans to reach an annual capacity of around 400 MWh.
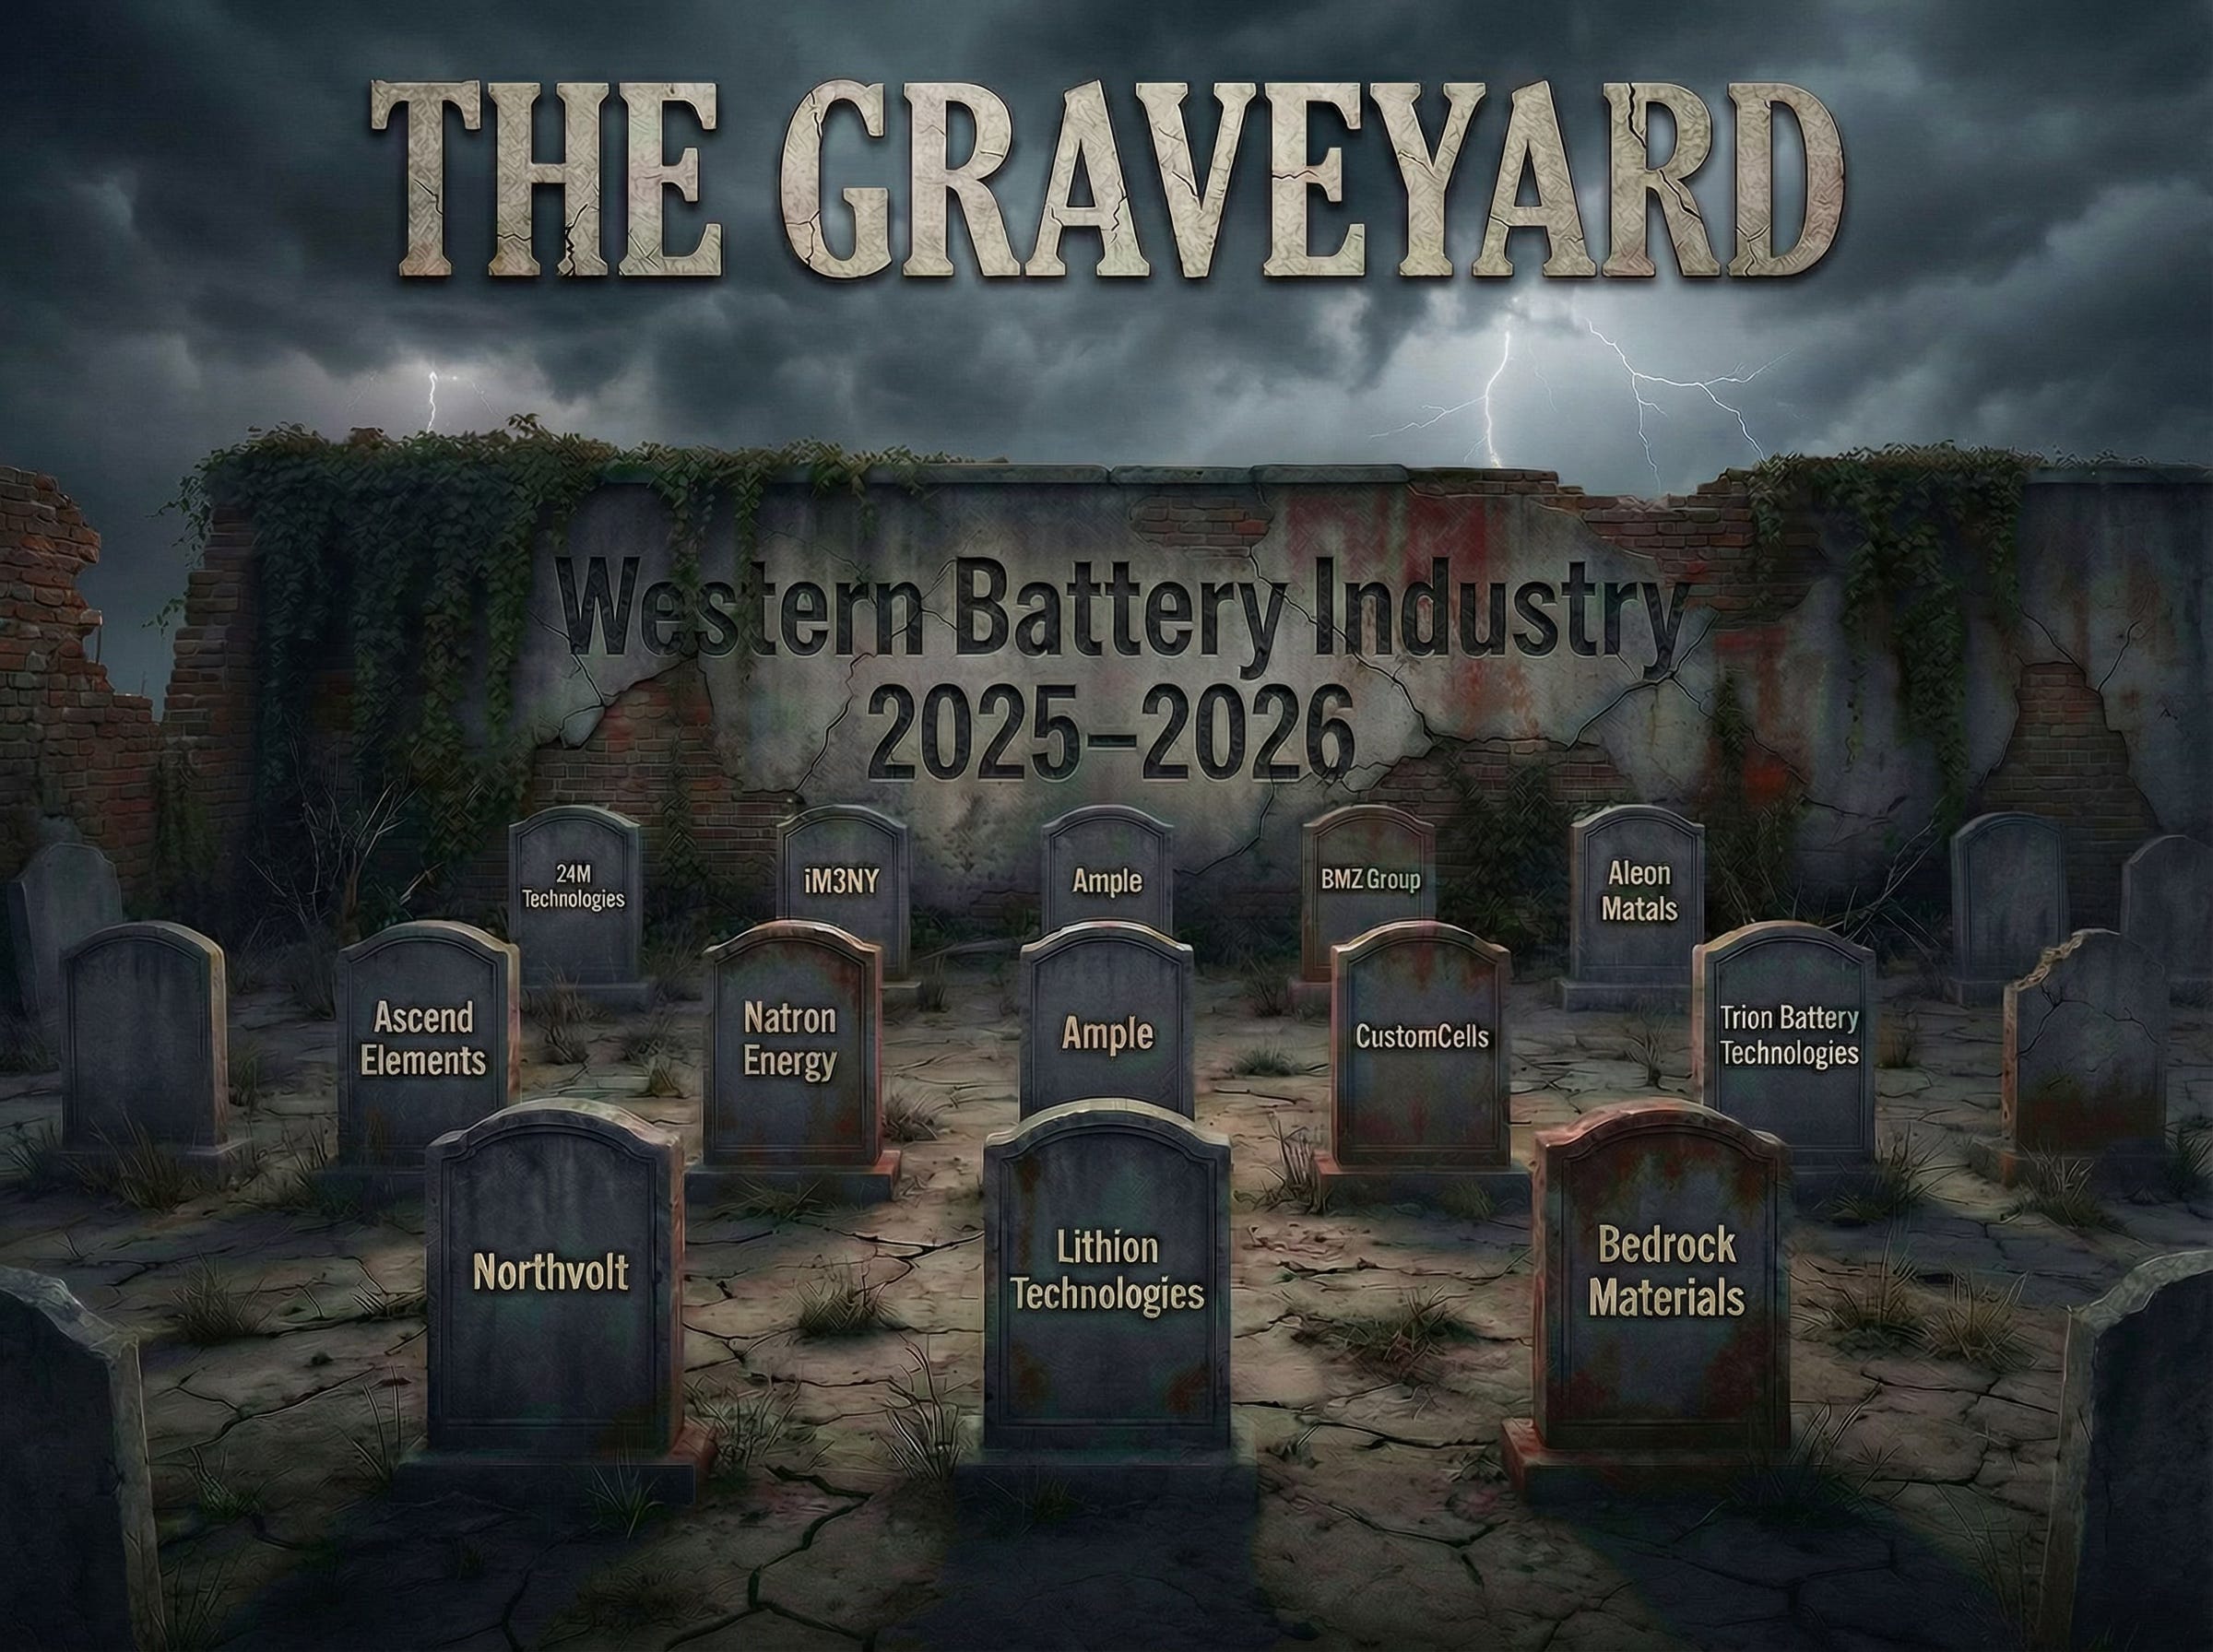
From January 2025 to April 2026, 14 Western battery companies went under despite raising more than $20 billion in total, with Northvolt accounting for $15 billion on its own.
Here’s the graveyard list of the 14 Western battery companies that went under
iM3NY (New York, US)
Bedrock Materials (US)
Northvolt (Sweden)
Li-Cycle (Canada/US)
CustomCells (Germany)
Powin (Oregon, US)
Aleon Metals (Texas, US)
Natron Energy (California/Michigan, US)
BMZ Group (Germany)
Lithion Technologies (Quebec, Canada)
Ample (California, US)
Trion Battery Technologies (Calgary, Canada)
24M Technologies (Massachusetts, US)
Ascend Elements (Massachusetts/Georgia/Kentucky, US)
The five deadly mistakes I keep seeing
The battery market grew in 2025, with CATL posting record numbers. These fourteen Western battery companies failed while the market around them kept growing. The same five mistakes show up in almost every filing.
1. They tried to scale or plan the next gigafactory before their first plant actually worked: Natron Energy, Ascend Elements, Li-Cycle, Lithion Technologies, Northvolt.
Natron opened a sodium-ion plant in Michigan in 2024, but UL certification delays blocked $25 million in booked orders, and the plant never stabilized. While Michigan was still struggling, Natron announced a $1.4 billion gigafactory in North Carolina, 40 times larger. The financing never came, and by September 2025, Natron was liquidating.
Ascend operated a Georgia battery recycling plant that required a full shutdown and rework under prior leadership, which court filing analysts on X called a “bonehead maneuver.”
While the Georgia plant was unstable, Ascend broke ground on a $1 billion-plus facility in Kentucky that attracted $16 million in contractor fraud claims. Georgia piled up $145 million in liens, and both projects ended up in bankruptcy.
Li-Cycle raised $1.7 billion and built five spoke facilities, but never finished the Rochester Hub that was supposed to process what they collected. Glencore bought the whole thing for a $40 million credit bid.
Northvolt raised $15 billion and planned gigafactories across Sweden, Germany, Poland, and Canada, yet the first plant in Sweden never reached its target capacity. After losing the BMW contract, Northvolt filed for bankruptcy with approximately $5.8 billion in debt.
Lithion completed its Saint-Bruno plant on June 3, 2024. On that same day, the CEO told the press, “This is just the beginning. We will build more recycling plants.” By October 2025, the company filed for creditor protection and laid off 45 people. The patented extraction technology had never been put into real use.
2. They never got to “real revenue”: 24M Technologies, iM3NY, Trion Battery Technologies, Bedrock Materials, and Natron Energy.
Five of the fourteen were pre-revenue or close to it when they went down.
24M was valued at over $1 billion on an IP licensing model that generated real output only through one licensee in Japan. They bet on a technology (semi-solid batteries) that only the Chinese have bet heavily on, and they developed their own.
iM3NY promised 2,500 jobs to New York State, but at the time of the filing, only 22 employees remained, and it had a net operating loss of $142.6 million.
Trion posted $466,000 in revenue against $16.5 million in costs. Bedrock’s CEO returned the money to investors and said the math no longer worked. Years of spending with no proof that the product could sell.
3. Bad management and sloppy execution: Ample, Powin, Ascend Elements, iM3NY, Northvolt.
An insider told Electrek that Ample suffered from “poor management due to inexperience, overhyped company statements, and inefficient use of money.”
Staff went from 198 to 2 before filing, and three ex-employees sued under the WARN Act for failing to give the required 60-day notice.
Powin came under public criticism over field safety and thermal problems. Former employees and industry insiders also described rushed deployments that later turned into expensive fixes.
The company also went through multiple leadership changes in the years before it filed
Ascend’s new CEO publicly highlighted the same pattern of fiscal and operational mismanagement.
iM3NY had local press reporting “faulty products and money mismanagement” before it ever filed.
4. Total concentration risk (everything riding on one thing). CustomCells, BMZ Group, Aleon Metals.
CustomCells bet on Lilium, the eVTOL company, and when Lilium went insolvent, CustomCells was stuck with tens of millions in unpaid bills.
BMZ lost its biggest energy-storage client and fell apart within weeks.
Aleon Metals operated a single facility in Texas, where a single SO2 scrubber failure reduced throughput by 96%. In each case, one bad break was enough to take down the entire company.
5. They promised the full chain but only built half of it: Li-Cycle, Lithion Technologies, Ascend Elements.
All three recyclers told the same story to investors and grant-makers: collect old batteries, break them into black mass, and refine that into battery-grade lithium, nickel, and cobalt. Full circle.
None finished the refining step. Lithion never used its patented extraction process. Li-Cycle’s Rochester Hub was never completed. Ascend’s Georgia line needed full rework.
Lithium prices dropped 70 to 80% from 2022 highs. Black mass alone could not pay the bills.
What this all really comes down to
None of these five problems is hard to see: scaling too fast, no revenue, bad management, concentration risk, and half-built value chains.
All five patterns come down to two things: execution and patience.
The technology in most of these companies worked. The market demand was there. What failed was the ability to get a plant running on budget before committing to the next one.
Cell production, recycling, storage integration: none of it scales fast.
CATL, BYD, Samsung SDI, and LG spent 15 years running small lines and fixing problems on the floor before committing to multi-gigascale production. They built operational knowledge one production cycle at a time.
Western companies tried to close that 15-year gap in under five years, mostly with capital and press releases.
Some of these assets have already changed hands.
Glencore operates Li-Cycle’s Spokes, Lyten acquired parts of Northvolt, SKion rescued BMZ, and FlexGen bid for Powin. The difference is who owns them.
The new owners now operate, or are close to operating, the same plants using the same technology in the same market. They bought the assets cheaply, but the real test begins now, especially for Lyten.
The West needs to change its mindset and drop the arrogance. China is the clear leader in technology, scale, pricing, and quality. Until that is accepted, serious progress will remain difficult.
Thanks for reading The Battery Chronicle!
If you find this kind of analysis useful, you may also be interested in two standalone resources I’ve built alongside the newsletter.
➟ The Battery Starter Kit - New 2025 market data added
➟ CATL Company Profile - New 2025 financial data (revenue, margin, GWh sales…), NING Service (aftersales), truck battery swapping (Qiji Energy) added.
In reality, the failures in the Western battery manufacturing industry extend well beyond the 14 start-ups Christopher Chico highlighted, such as Northvolt. What many people have already forgotten is Tesla’s 4680 battery project.
Five years ago, Elon Musk projected that Tesla would reach 100 GWh of 4680 battery capacity by 2022, enough to support roughly 1.3 million vehicles. But a Reuters investigation at the end of 2023 showed that actual output from the Austin factory was running far below that target, with Tesla internally described as being stuck in “battery production hell.” This shows that the project was not canceled; rather, the most difficult part of the process, especially large-scale manufacturing and yield control, fell far short of the original plan.
Although Tesla’s large battery project did not fail in the same way Northvolt did, through a broken funding chain and corporate collapse, it still went through a very typical form of partial failure, or delayed delivery, in which the technical logic was sound but the manufacturing ramp proved far slower than expected. The project is not dead. It has instead shifted from an originally over-promised revolutionary project into one that is still moving forward, but looks much more like a slow, difficult traditional manufacturing effort than the market first imagined. Tesla was simply more fortunate than those 14 start-ups such as Northvolt, because it had an automotive business, cash flow, brand strength, capital-market access, and an external supplier system to absorb the shock.
What makes Christopher Chico’s piece valuable is that he does not reduce the repeated failures of Western battery companies to slogans such as “China’s subsidies are too strong,” “China overcapacity,” or “the market environment was too weak.” Instead, he brings the discussion back to the most fundamental questions in manufacturing: Can the production line actually run? Can yields improve over time? Can cash flow hold up? Does management have the ability to land a complex industrial project in the right sequence and at the right pace?
That said, his final conclusion, that all five categories of failure ultimately come down to insufficient execution and insufficient patience, is still too simplistic. From the perspective of China’s lithium battery industry experience, the real difference is not that China succeeded merely because it was “more hardworking” or “more patient.” Rather, China succeeded through an entire organizational system that is much more closely aligned with the actual laws of industrial development.
First, Chinese companies did not begin by fixating on the ultimate end-state scale. They first built process capability through real orders that kept expanding over time. And the reason Chinese firms were able to do this is not because they were somehow naturally more rational. It is because behind them stood a huge domestic market, dense trial-and-error scenarios with customers, fast-feedback supply chain networks, and EV and energy-storage customers willing to iterate alongside them. In other words, China’s “patience” was not an abstract virtue. It was patience generated by an industrial ecosystem.
Second, the core of the Chinese experience is not the success of a single factory, but the fact that the entire supply chain climbed the ramp together. In the battery industry, yield, cost, performance, and delivery capability are never determined by a single cell maker alone. They are pulled upward collectively by upstream materials, equipment, structural components, cathodes, anodes, electrolytes, separators, BMS, pack integration, and EV and storage customers. One major reason China was able to achieve scale more easily is that large numbers of suppliers, equipment makers, customers, local governments, and engineering teams were all operating within the same geographic and institutional space, allowing for extremely fast coordination. The Chinese experience shows that real execution capability is often the execution capability of an entire industrial network, not just the capability of a single CEO.
In the end, competition in the battery industry is not fundamentally about who invents the technology first. It is about who can first turn technology into industrial capability that can be replicated continuously at scale.
Looks like RecycLiCo was smart.
They have recycling patents with up to 99% recovery.
Now they are also focused on refining.
Wild to see as the dust settles RecycLiCo is still moving forward.